A company can be profitable on paper and still run out of cash before the next payroll, supplier payment, or loan installment falls due. When that pressure builds, directors often hear two proposed solutions: debt restructuring versus refinancing. They are not interchangeable. One changes the terms or treatment of debt already causing distress; the other replaces existing borrowing with new funding. Choosing the wrong route can consume valuable time, weaken negotiations with creditors, and place the business under greater pressure.
For Malaysian companies and regional groups, the decision must be made against the actual condition of the business, its creditor profile, available security, and the urgency of cash-flow demands. The right answer is rarely the cheapest-looking interest rate. It is the option that gives a viable business enough financial and operational room to recover.
Debt restructuring versus refinancing: the core difference
Debt restructuring is a negotiated or formal process to change how existing obligations will be repaid. The company may seek longer repayment periods, reduced installments, a temporary payment standstill, interest relief, a conversion of debt into equity, or a compromise of the amount due. It is generally used when the current capital structure is no longer sustainable under the company’s forecast cash flow.
Refinancing means obtaining a new loan or credit facility to repay, replace, or consolidate existing debt. The new facility may have a longer tenure, different security, lower rate, improved repayment profile, or a new lender. It works best where the business remains creditworthy and can demonstrate that future cash generation will service the replacement debt.
The distinction matters because refinancing assumes a lender is prepared to advance fresh capital. Restructuring begins with the creditors already exposed to the business. A lender may require refinancing as part of a broader restructuring, but new finance alone does not solve a business that cannot meet its obligations after the facility is drawn.
When refinancing can protect the business
Refinancing is often appropriate when the company’s financial difficulty is largely structural or temporary rather than fundamental. For example, a manufacturer may have sound orders and acceptable margins but be carrying short-term facilities used to finance long-lived equipment. Replacing those facilities with a properly matched term loan can reduce monthly debt service and stabilize working capital.
It can also help where several expensive facilities have created an unmanageable repayment schedule. Consolidating debt into one facility may simplify administration, improve visibility over cash commitments, and reduce the risk of accidental default across multiple lenders.
A refinancing proposal is stronger when management can show a credible operating plan, current financial information, realistic cash-flow forecasts, and sufficient asset value or earnings capacity to support the new facility. A lender will examine more than historical revenue. It will test customer concentration, overdue receivables, contingent liabilities, director guarantees, security coverage, and the assumptions behind projected recovery.
Refinancing has trade-offs. A lower monthly payment may arise because the debt term has been extended, increasing the total interest paid. New security may expose assets previously outside the lender’s reach. Personal guarantees, tighter covenants, or enhanced reporting may be required. If the company uses refinancing only to meet overdue payments without correcting recurring losses, it has postponed the problem rather than resolved it.
When debt restructuring is the more realistic route
Debt restructuring becomes necessary when the company cannot obtain sufficient new funding on workable terms, or when its debt burden materially exceeds what its business can repay. This may follow a sustained fall in sales, delayed collections, cost inflation, a failed project, litigation exposure, or a period of trading losses.
In these cases, creditor engagement should begin before enforcement action limits the available options. A restructuring may involve one key lender, trade creditors, landlords, related-party creditors, bondholders, or a combination of stakeholders with competing priorities. The process requires a clear picture of what each creditor is owed, what security exists, and what outcome is likely if the business continues, is sold, or enters liquidation.
An informal workout can be effective where creditors are few and aligned. Management might negotiate a standstill while it disposes of non-core assets, collects major receivables, reduces costs, or introduces new equity. The company must be transparent enough to maintain confidence while protecting commercially sensitive information. Unsupported promises and optimistic forecasts usually accelerate creditor resistance.
Where informal negotiations cannot create a binding solution, Malaysia’s Companies Act 2016 provides formal rescue mechanisms. A Scheme of Arrangement can enable a company to propose a court-supervised compromise or arrangement with creditors. Judicial Management may provide protection and an opportunity to rehabilitate a company through an appointed judicial manager, subject to the statutory requirements. A Corporate Voluntary Arrangement may be relevant for eligible private companies seeking a supervised proposal without commencing formal court proceedings.
These mechanisms are not automatic cures. They require careful preparation, a viable rehabilitation case, and disciplined stakeholder communication. They may also affect trading relationships, credit availability, management control, and the company’s reputation. Yet for a viable company facing immediate creditor pressure, a formal process can create the structure needed to preserve value that would otherwise be lost through piecemeal enforcement.
The question directors should ask first
The critical question is not, “Can we obtain another loan?” It is, “What level of debt can this business sustainably carry after realistic operating costs, taxes, capital expenditure, and working-capital needs?”
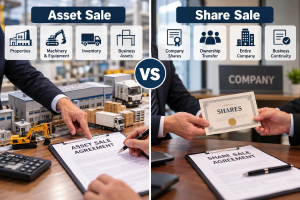
If the forecast shows the company can repay all principal and interest but needs a better maturity profile, refinancing may be the right tool. If the forecast shows that obligations must be reduced, deferred, compromised, or converted for the company to survive, restructuring is likely required. If neither scenario produces a credible recovery, directors should consider an orderly sale, asset realization, or voluntary liquidation rather than allowing losses to deepen.
This assessment should be based on a short-term cash-flow model and a longer-term business plan. The short-term model identifies whether the company can continue meeting essential commitments over the next 13 weeks. The longer-term plan tests whether the proposed capital structure works after the immediate crisis has passed.
How creditor dynamics affect the choice
A business with one secured bank lender faces a different challenge from one with numerous trade creditors and statutory arrears. A bank may be prepared to refinance if security is adequate and management can restore confidence. Trade creditors may be more focused on payment certainty, continued orders, and equal treatment against competing suppliers.
Secured creditors hold significant influence because they may enforce against charged assets. Unsecured creditors may support a restructuring if it produces a better return than liquidation. Employees, customers, landlords, shareholders, and guarantors can also be materially affected. A workable plan recognizes these interests rather than treating debt as a purely banking issue.
Directors should also avoid selectively paying certain creditors without understanding the implications for the wider creditor body and potential formal proceedings. When insolvency risk is rising, decisions should be documented, commercially justified, and supported by professional advice. The aim is to protect enterprise value and act responsibly, not merely delay the next demand.
A practical decision process
Before approaching lenders or proposing a creditor compromise, management should establish the facts. That means reconciling all debt, confirming security documents and guarantees, identifying overdue liabilities, and preparing a weekly cash-flow forecast. The business must also identify the operational actions that will support recovery, such as collecting receivables, reducing unprofitable work, renegotiating procurement terms, selling non-core assets, or bringing in equity.
The funding requirement should then be separated into three categories: money needed to meet immediate obligations, capital needed to support normal operations, and any long-term debt that the business cannot realistically service. This prevents a common mistake: using expensive short-term finance to cover a permanent balance-sheet problem.
Management can then present creditors with a coherent proposal. For refinancing, that proposal centers on repayment capacity, security, and facility structure. For restructuring, it centers on the comparative outcome: what creditors receive under the proposal versus the likely result of enforcement or liquidation. In both cases, credibility comes from evidence, not assurances.
EST Advisory Management helps companies assess these alternatives in the context of their cash position, creditor pressure, and available statutory options. The objective is not to force every business into a formal process. It is to identify the fastest credible route to stabilize obligations, preserve value, and give decision-makers control of the next step.
Do not wait for the decision to be made by creditors
Refinancing is most effective before credit quality deteriorates. Restructuring is most effective before fragmented enforcement destroys the value of the underlying business. Once bank accounts are frozen, key suppliers withdraw terms, or winding-up pressure escalates, the number of workable choices narrows quickly.
A financially stressed company does not need vague reassurance. It needs an honest assessment of whether its debt can be refinanced, must be restructured, or should be resolved through a controlled exit. Acting while there is still cash, information, and stakeholder confidence gives directors the best chance to protect the business and move forward on terms they have helped shape.